All Categories
Featured
Reviewing Top-Rated Medicare Supplement Options
Table of Contents
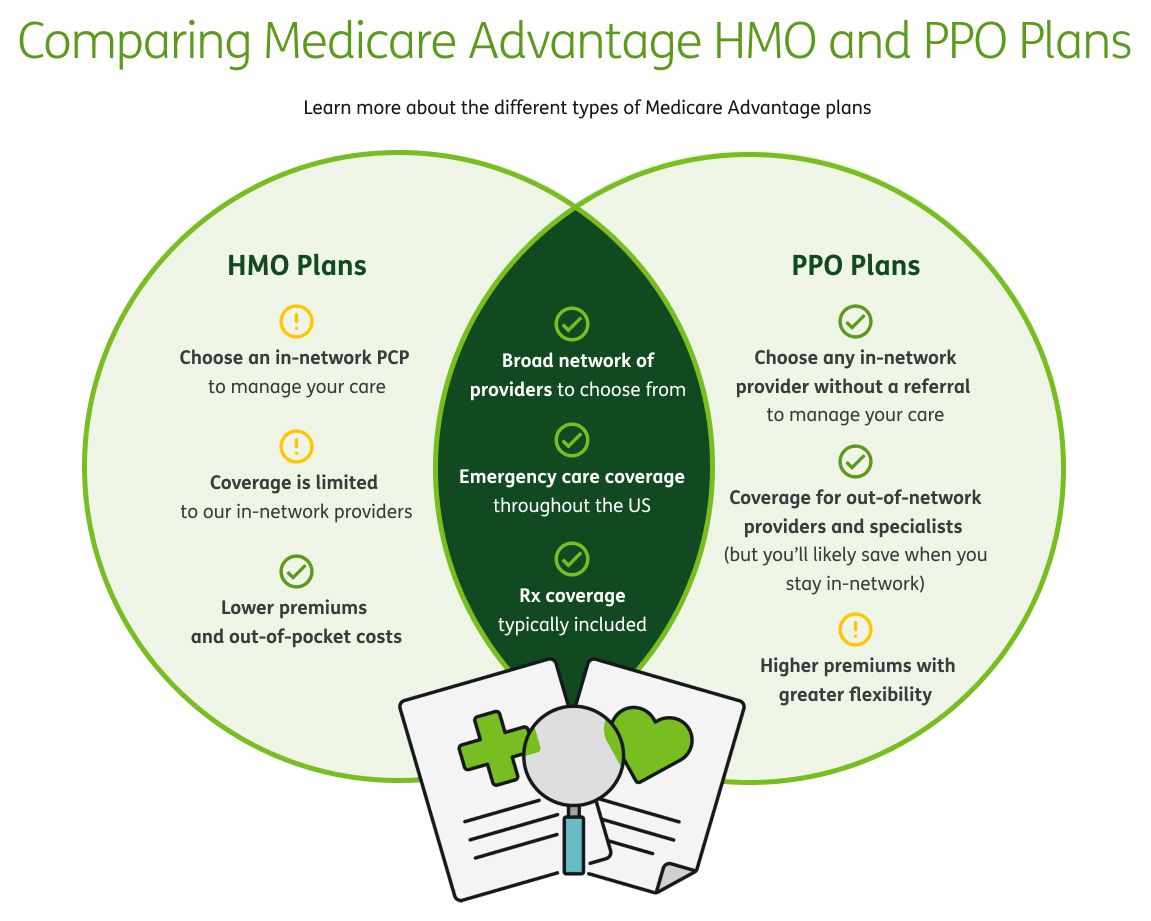
Understanding the differences between specific health plans, like an HMO and a PPO plan, is required to protect the right health coverage for you, your household, or your employees. In this article, we'll stroll you through the key differences in between HMO and PPO plans, evaluate their advantages and disadvantages, and show you how each plan works with a health compensation plan (HRA).
Due to the fact that of this, these policies use lower premiums and out-of-pocket expenses. PPO plans provide more flexibility in selecting health suppliers and services than HMO strategies. But, they frequently have higher premiums and deductibles, and require policyholders to file their own claims for out-of-network care, which can be complicated and lengthy.
An HMO is a kind of health insurance where a group of network doctors, hospitals, and other medical care suppliers agreement with an insurance company to offer policyholders numerous covered services and items in exchange for a premium. Providers within the HMO network consent to provide care to insurance policy holders at a lowered rate.
In 2023, 13% of employees in the U.S. with health insurance coverage enrolled in an HMO plan1. Since these policies usually have lower premiums and out-of-pocket costs compared to other types of health insurance, they can look like an attractive choice for those trying to find protection. But, the lower general costs included specific restrictions.
Comparing HMO Provider Access and Monthly Costs
Their HMO also won't cover the costs of out-of-network care or treatment from an expert that happened without a PCP referral, other than if a policyholder needs emergency situation care. Before figuring out if an HMO matches you or your organization, you must analyze the benefits and drawbacks. HMO plans normally have low premiums and copayments.
Your plan will also typically cover in-network professional care with only a small copay for services. When you enlist in an HMO plan, you need to pick a PCP who will be your main point person to reach out to when you need care. In return, they collaborate your care, manage your general treatment, and make recommendations for specialists.
Additionally, your PCP acts as your medical supporter, and you may develop a strong bond with them, resulting in you getting much better and more constant care. While these benefits of HMO strategies may seem luring, there are prospective drawbacks that you need to think about before registering. If you want your HMO to cover the cost of your care, you must receive care from a specific network of companies in your location.
If you see a non-network company, you'll be responsible for your whole bill without the assistance of your insurance provider. If you require to check out an expert for treatment, you should ask your PCP for a recommendation for an in-network specialist ahead of time. If your PCP does not refer you, you must pay the entire cost of the bill alone, which can be costly.
Your policy will lay out the circumstances that it thinks about an emergency situation. If your emergency situation does not fit the requirements in your strategy, you'll need to foot the bill on your own. In 2023, the average annual premium for a group HMO strategy was $8,203 for self-only coverage and $23,758 for family coverage2.
Smart Financial Strategies Using Modern Life Insurance
Like other types of health strategies, HMO policies might have an annual deductible. A deductible is the set quantity of cash a strategy individual should pay out-of-pocket before their insurer starts to cover their medical care expenses.
KFF discovered that 33% of people registered in a self-only HMO don't have a deductible3. Last but not least, the 2023 out-of-pocket optimum for an Affordable Care Act (ACA) Market strategy was $9,100 for self-only protection and $18,200 for household coverage4. In 2024, the maximum out-of-pocket limitation increased to $9,450 for individuals and $18,900 for households.
A PPO policy is a kind of health strategy in which an insurance company contracts with medical professionals, healthcare experts, and medical facilities to produce a list of "favored" doctor for insurance policy holders. When people with a PPO strategy get medical care from an in-network supplier, their health insurance company pays the provider at an agreed-upon reduced rate.
PPOs are the most typical plan that employers provide. In 2023, 47% of people with a group health insurance plan have a PPO2. These plans are popular due to the fact that they do not require members to choose a PCP before enrolling and enable members to pick from a bigger variety of in-network companies than they can with an HMO strategy.
PPO strategies provide numerous benefits that make getting medical care a hassle-free and favorable experience. PPO plans have a large network of suppliers offering the very same types of medical services with set similar prices.

Latest Posts
Reviewing Top-Rated Medicare Supplement Options
How to Choose Life Insurance in a Changing Economy
Planning for End-of-Life Costs with Local Final Expense Plans